Credit card rewards may appear as money yet credit card rewards are paid for by several sources in the credit card system. When we ask. Who pays for credit card rewards the answer involves card issuers, merchants and indirectly consumers who pay interest or fees. Understanding this system helps us choose rewards cards wisely and avoid losing credit card rewards to costs.
Who Pays for Credit Card Rewards?
At the level card issuers pay for credit card rewards such as cash back and points. Banks fund these programs with money from interest cardholder fees and card transactions. Therefore, when we ask who pays for credit card rewards we should consider the payment ecosystem.
Merchants normally pay interchange fees when customers use credit cards. Part of this money can help issuers fund credit card rewards programs.
How Credit Card Issuers Fund Rewards
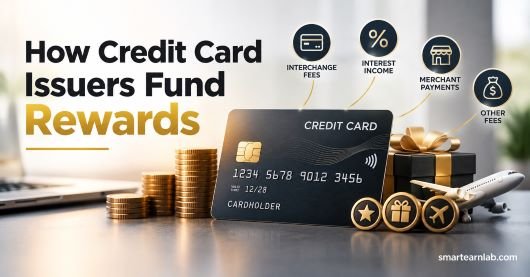
1. Interest Charges
Interest is a source of credit card revenue. If we carry a balance after the billing cycle the issuer can charge interest based on the cards APR.
Therefore we should avoid treating credit card rewards as a reason to spend more. Paying the statement balance in full and on time helps us keep more of the value from cash back and points.
2. Credit Card Fees
Annual fees, fees, balance transfer fees, cash advance fees and foreign transaction fees can also generate revenue.
A premium card makes sense when its benefits can reasonably outweigh the annual cost.
3. Merchant Interchange Fees
Merchants normally pay interchange fees as part of processing credit card transactions.
This means the answer to who pays for credit card rewards is not limited to cardholders. Merchants are a part of the system because transactionrelated fees help support credit card rewards.
How to Earn Rewards Without Losing Money
We can maximize credit card rewards by using a card for purchases we already planned to make than increasing spending to earn points.
Importantly paying the balance in full each month can help us avoid purchase interest. We should also avoid late fees, cash advances and other charges that reduce credit card rewards value.
We should never buy something simply because a promotion offers points or the cash back. A $100 purchase remains a $100 expense the even when it earn credit card rewards.
The Bottom Line
So, who pays for credit card rewards? Issuers fund credit card rewards with revenue from interest, fees and card transactions while merchants contribute through interchange‑related costs. Consumers can indirectly bear part of the cost through interest and the fees.
Credit card rewards can be valuable when they come from planned spending and when we understand the card costs. The smartest approach is to the treat credit card rewards as a bonus, not a reason to spend. By choosing a card avoiding unnecessary fees and paying balances in full we can capture more credit card rewards value while keeping credit card costs under control over time and each month with confidence and consistency.
[Cardholder uses card] –> [Merchant processes payment]
–> [Interchange fees]
–> [Issuer revenue]
–> [Rewards funding]
–> [Interest and fees]
–> [Cash Back, Points or Miles]
FAQs
Who pays for credit card rewards?
Credit card issuers mainly fund rewards through interest or fees and transaction revenue.
Do merchants pay for credit card rewards?
Yes merchants pay interchange fees on credit card transactions which help support rewards programs.
Are credit card rewards really free?
Not always. Interest and fees can reduce or completely offset the value of your rewards.
How can we maximize credit card rewards?
Use rewards cards for planned purchases and pay the balance in full each month.
Can credit card rewards cost us money?
Yes unnecessary spending, interest and annual fees can cost more than the rewards earned.
